Louisville Kentucky VA Residual Income Guidelines
Residual Income
VA residual income is one of the major underwriting guidelines required to qualify for a Louisville Ky VA mortgage. Residual income is calculated by determining the gross monthly income of the veteran and spouse. Then, ... deduct from that total gross monthly income the following monthly expenses:
0

State Taxes
Social Security
Federal Taxes
Proposed new monthly house payment (PITI: principle, interest, taxes and insurance)
Estimated Maintenance and Utilities
Monthly Child Care Expense
Alimony or Child Support
Monthly consumer debt payments: installment and revolving credit cards
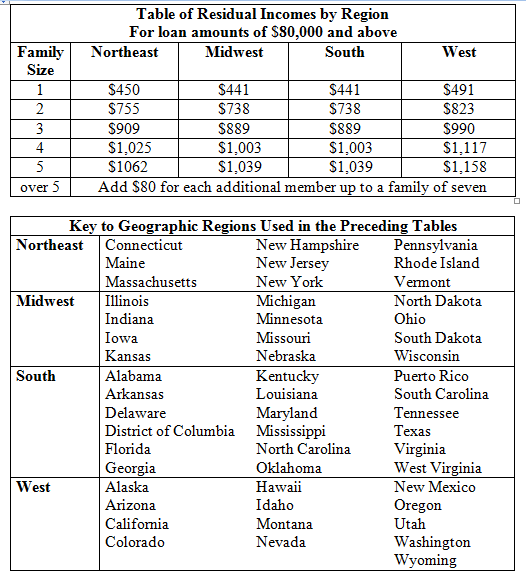
The balance remaining is "residual income" and will determine whether the borrower qualifies based on the table below.
Louisville Ky VA's minimum residual incomes (balance available for family support) are a guide. They should not automatically trigger approval or rejection of a loan. Instead consider residual income in conjunction with all other credit factors.
An obviously inadequate residual income alone can be a basis for disapproving a loan.
If residual income is marginal, look to other indicators such as the applicant's credit history, and in particular, whether and how the applicant has previously handled similar housing expense.
Consider whether the purchase price of the property may affect family expense levels. For example: A family purchasing in a higher priced neighborhood may feel a need to incur higher-than-average expenses to support a lifestyle comparable to that in their environment. Whereas a substantially lower priced home purchase may not compel such expenditures.
Also consider the ages of the applicant's dependents in determining the adequacy of residual income. Count all members of the household (without regard to the nature of the relationship) when determining "family size," including:
An applicant's spouse who is not joining in title or on the note, and
Any other individuals who depend on the applicant for support. For example, children from a spouse's prior marriage who are not the applicant's legal dependents.
Exception: The lender may omit any individuals from "family size" who are fully supported from a source of verified income which, for whatever reason, is not included in effective income in the loan analysis.
For example: A spouse not obligated on the note who has stable and reliable income sufficient to support his or her living expenses, or a child for whom sufficient foster care payments or child support is received regularly.
Reduce the residual income figure (from the following tables) by a minimum of 5% if the applicant or spouse is an active-duty or retired serviceperson, and there is a clear indication that he or she will continue to receive the benefits resulting from use of military-based facilities located near the property.
Use 5% unless the Louisville Ky VA office of jurisdiction has established a higher percentage, in which case, apply the specified percentage for that jurisdiction.
Louisville Kentucky VA Residual Income Guidelines
One of the most important — and often overlooked — requirements for a VA home loan in Louisville and across Kentucky is
residual income. This rule ensures veterans and their families have enough money left over each month to cover
daily living expenses after paying the mortgage, taxes, and other obligations.
What Is Residual Income?
Residual income is the amount of money you keep after paying:
- Federal, state, and Social Security taxes
- Your new house payment (PITI: principal, interest, taxes, insurance)
- Utilities and estimated home maintenance
- Child care, alimony, or child support
- Consumer debts like car loans and credit cards
The VA requires a minimum residual income based on family size and region. Louisville and all of Kentucky fall into the
South Region.
VA Residual Income Chart for Kentucky (Loans Over $80,000)
| Family Size |
Minimum Residual Income |
| 1 | $441 |
| 2 | $738 |
| 3 | $889 |
| 4 | $1,003 |
| 5 | $1,039 |
Add $80 for each additional family member beyond five.
Why It Matters
Residual income helps prevent veterans from becoming “house poor.” Even if your debt-to-income ratio looks good,
the VA double-checks that you’ll still have enough left over each month to take care of your family.
If you’re slightly below the guideline, other strengths like good credit history or savings may help, but
falling far short of the requirement can be a deal breaker.
FAQ: Louisville VA Residual Income
Q: Who counts toward family size?
A: Everyone in the household — including a spouse not on the loan and dependents — unless they are fully supported by
outside verified income.
Q: Can I still be approved if my residual income is short?
A: NO
Q: How does this differ from debt-to-income ratio?
A: DTI looks only at income versus debt. Residual income measures the cash left over for everyday living after those debts are paid.
Kentucky VA Residual Income Guidelines Slides Graphs
A Kentucky Veteran's Guide to VA Residual Income
Introduction: What Kentucky Veterans Need to Know
As a Kentucky veteran, you have access to one of the most powerful home loan programs available: the VA home loan. One of the key requirements for this loan is meeting the VA's residual income guidelines. This guide is designed to help you understand what residual income is, how it's calculated, and what the specific requirements are for veterans living in Kentucky.
Kentucky is part of the VA's South region, which has its own set of residual income requirements. Understanding these requirements will help you prepare for the home loan process and increase your chances of getting approved for a VA loan.
Residual Income Requirements for Kentucky
As a resident of Kentucky, you fall under the VA's South region for residual income calculations. The amount of residual income you'll need depends on the size of your family and the amount of your loan. Here's a table that breaks down the requirements for the South region:
Residual Income by Region for Loan Amounts of $80,000 and Above
| Family Size | Northeast | Midwest | South | West |
| 1 | $450 | $441 | $441 | $491 |
| 2 | $755 | $738 | $738 | $823 |
| 3 | $909 | $889 | $889 | $990 |
| 4 | $1,025 | $1,003 | $1,003 | $1,117 |
| 5 | $1,062 | $1,039 | $1,039 | $1,158 |
For families larger than 5, add $80 for each additional member up to a family of seven.
It's important to remember that these are the minimum requirements. If your debt-to-income ratio is higher than 41%, your lender will likely require your residual income to be at least 20% higher than the amounts listed in the table.
Local Resources for Kentucky Veterans
If you have questions about your VA loan benefits or need assistance with the home loan process, there are several resources available to you in Kentucky:
•Kentucky Department of Veterans Affairs (KDVA): The KDVA is your primary advocate for all veterans benefits in Kentucky. They can provide you with information and assistance on a wide range of topics, including VA home loans. You can visit their website at veterans.ky.gov. •VA Regional Loan Center: The VA Regional Loan Center for Kentucky is located in St. Paul, Minnesota. However, you can find a list of VA-approved lenders in Kentucky on the VA website.
•Local Veteran Service Organizations: Organizations like the Veterans of Foreign Wars (VFW) and the American Legion have posts throughout Kentucky and can provide you with support and guidance.
By understanding the VA residual income requirements and utilizing the resources available to you, you can make your dream of homeownership a reality.
Want to See If You Qualify?
I’ll run your residual income numbers and give you a free VA loan pre-qualification for Louisville or anywhere in Kentucky.
📞 Call/Text Joel Lobb at (502) 905-3708
Apply Online Now
EVO Mortgage | NMLS #1738461 | Joel Lobb NMLS #57916 | Equal Housing Lender

VA Residual Income Questions
VA Residual Income FAQ — Answered by a Kentucky VA Lender
What is the VA residual income chart for 2026?
Kentucky is in the VA's South region. For loan amounts over $80,000, the minimum monthly residual income is:
| Family size | Loan over $80,000 | Loan under $80,000 |
|---|
| 1 | $441 | $382 |
| 2 | $738 | $641 |
| 3 | $889 | $772 |
| 4 | $1,003 | $868 |
| 5 | $1,039 | $902 |
Add $80 for each additional family member beyond five (for loans over $80,000). These VA figures apply to every Kentucky county, including Louisville, Lexington, and Northern Kentucky.
How do I calculate my VA residual income?
Start with the gross monthly income of the veteran and spouse, then subtract federal and state taxes, Social Security, the proposed new house payment (principal, interest, taxes, and insurance), estimated maintenance and utilities (most lenders use about 14 cents per square foot of the home), child care, alimony or child support, and monthly payments on installment loans and credit cards. Whatever is left over is your residual income.
Can I still get approved if my residual income is below the VA guideline?
Falling slightly short is not an automatic denial — the VA tells lenders that residual income should not automatically trigger approval or rejection. If you are close to the number, compensating factors like strong credit history, savings after closing, or a history of handling similar housing payments can carry the file. Falling far below the guideline, however, is usually a deal breaker on its own.
Who counts as family size for VA residual income?
Everyone in the household counts, whether or not they are on the loan — including a spouse who is not on the note and children from a spouse's prior marriage. The exception is anyone fully supported by verified income that is not being counted in the loan, such as a child receiving sufficient foster care payments or child support. Active-duty and retired service members near a military base may also have their required figure reduced by 5%.
What is the VA 20% residual income rule when DTI is over 41%?
If your debt-to-income ratio is above 41%, VA guidelines require your residual income to exceed the chart minimum by at least 20%. For example, a Kentucky family of four with a DTI over 41% would need roughly $1,204 in monthly residual income instead of $1,003. This is the most common way strong residual income saves a VA loan that would fail on DTI alone.
How is residual income different from debt-to-income ratio?
DTI is a percentage — your monthly debts divided by your gross income. Residual income is a dollar amount — the actual cash left over each month after taxes, the new house payment, utilities, and debts are paid. The VA checks both because a family can have an acceptable DTI on paper and still not have enough real money left to live on. Residual income is the VA's guard against becoming house poor.
Want me to run your residual income numbers before you house-shop? Call or text me at 502-905-3708, or start your free pre-qualification — I lend on VA loans across all 120 Kentucky counties.


 Call/Text -


