Posts

Showing posts with the label FHA Loans
Every Kentucky Loan Type. One Local Expert.
Whether you’re buying your first home, using down payment assistance, or rebuilding credit — there’s a program that fits. Compare them side by side before you commit.

🏠 FHA Loan

The go-to for first-time buyers and 580+ credit. Low down payment and flexible guidelines.

3.5% down · 580+ creditLearn More →

🎖 VA Loan

Zero down and no monthly mortgage insurance for veterans and active-duty service members.

$0 down · VA eligibleLearn More →

🌾 USDA Loan

100% financing for eligible rural and suburban Kentucky buyers within income limits.

$0 down · USDA areasLearn More →

🏛 KHC Assistance

Kentucky Housing down payment assistance for first-time and repeat buyers.

Up to $12,500 assistanceLearn More →

📈 Conventional

Best long-term value for stronger credit. PMI cancels at 20% equity, unlike FHA.

3% down · 620+ creditLearn More →

💰 Zero Down Options

Every route to buying with nothing down in Kentucky — VA, USDA, and KHC combos.

$0 down programsLearn More →

🌟 First-Time Buyers

All Kentucky first-time homebuyer programs compared in plain English.

Programs & grantsLearn More →

📊 Credit Scores

What score you actually need for each loan type in 2026 — and how to raise yours.

By loan programLearn More →

How Much House Can I Afford in Kentucky? 2026 DTI Limits by Loan Program

Image
By Joel Lobb, Kentucky Mortgage Loan Officer · NMLS #57916 · Updated September 24, 2026 Short answer: Kentucky lenders decide how much you qualify for using your debt-to-income ratio (DTI) . Your new house payment usually needs to stay near 29–31% of your gross monthly income , and your house payment plus all other debts can reach 41–50% depending on the loan program. A household earning $75,000 with $450 a month in debts typically qualifies for about $219,000 (USDA) to $303,000 (conventional) at today's rates. Your loan program sets the DTI limit, and the DTI limit sets your price range. "How much house can I afford?" is the first question almost every Kentucky homebuyer asks me, and online calculators rarely agree. That is because each loan program (FHA, VA, USDA, KHC, and conventional) uses different debt ratio limits, mortgage insurance, and down payments. This guide shows you exactly how lenders run the numbers, gives you a calculator built on Kentucky a...
Getting a Kentucky Mortgage in 3 Simple Steps
No confusing paperwork trails. No surprise fees. A clear path from first call to keys in hand.
01

💬 Get Pre-Qualified

Free application review with same-day answers. We look at your credit, income, and goals — no cost, no obligation, no pressure.

02

📋 Compare Your Options

FHA vs. Conventional vs. USDA vs. KHC — run side by side with your actual numbers so you see the real payment before you commit.

03

🏠 Close & Get Your Keys

Guided from contract to closing — appraisal, title, and underwriting coordinated so you always know what happens next.

Watch: Kentucky Mortgage Guides
Straight answers from my YouTube channel — no jargon, no sales pitch.
▶ More videos on my YouTube channel →
Joel Lobb and family - Kentucky mortgage loan officer
Kentucky Local. Not a Call Center.

Hi, I’m Joel Lobb — a Kentucky dad who’s spent 20+ years helping families across all 120 counties buy their first home. When you call, you get me — not a phone tree. Questions on a Saturday morning? I answer.

1,300+ Kentucky families have trusted me with their mortgage — from Louisville to Lexington to the smallest towns in the state. Free application reviews, same-day pre-approvals, and honest answers about what you actually qualify for.

See What You Qualify For →

Kentucky FHA Mortgage Information

Image
Louisville Kentucky Mortgage Lender for FHA, VA, KHC, USDA and Rural Housing Kentucky Mortgages: Kentucky FHA Mortgage Information :   How to Qualify For a Kentucky FHA Mortgage Loan 1. Low Down Payment   –  FHA Mortgage Loans only require a 3.5% down payment. And what m...

Kentucky FHA Mortgage Guidelines

🏠 Kentucky FHA Loan Guidelines for 2026 Everything Kentucky homebuyers need to know — updated for 2026 with the latest loan limits, credit score requirements, down payment assistance, and more. FHA loans have been the go-to mortgage solution for Kentucky first-time homebuyers for decades — and in 2026, they remain one of the most flexible and accessible loan programs available across all 120 Kentucky counties. Whether you're buying your first home in Louisville, Lexington, Bowling Green, or a small rural community, this guide covers everything you need to know before you apply. 📊 2026 FHA Loan Limits in Kentucky Effective January 1, 2026, FHA increased the baseline loan limit for a single-family home to $541,287 — up from $524,225 in 2025. That's an increase of approximately $17,000, giving Kentucky buyers more purchasing power. Kentucky uses the national floor limit across all 120 counties, with no high-cost county designations. Property ...

2025 Kentucky FHA Loan Requirements & Limits

Image
2025 Kentucky FHA Loan Requirements: Credit, Down Payment, DTI & Loan Limits 2025 Kentucky FHA Loan Requirements & Loan Limits Updated for 2025! FHA loan limits are higher across Kentucky. The new single-family limit is $524,225 —an increase of $25,968 from last year. That means you can buy more home with just 3.5% down! FHA Loan Requirements in Kentucky – 2025 Snapshot Minimum Credit Score: 580+ (3.5% down); 500–579 (10% down) Minimum Down Payment: 3.5% (with 580+ score) Debt-to-Income (DTI) Ratio: Typically up to 57% (with strong credit) Bankruptcy Wait Period: 2 years from Chapter 7 discharge, 1 year for Chapter 13 (with on-time payments) Foreclosure Wait Period: 3 years Loan Limits: $524,225 (1-unit); $671,200 (2-unit); $811,275 (3-unit); $1,008,300 (4-unit) Property Type: Must be your primary residence Loan Insurance: Upfront (UFMIP) + monthly MIP required ...

Kentucky FHA Mortgage Loans vs Kentucky USDA Rural Housing Loans Compared

Image
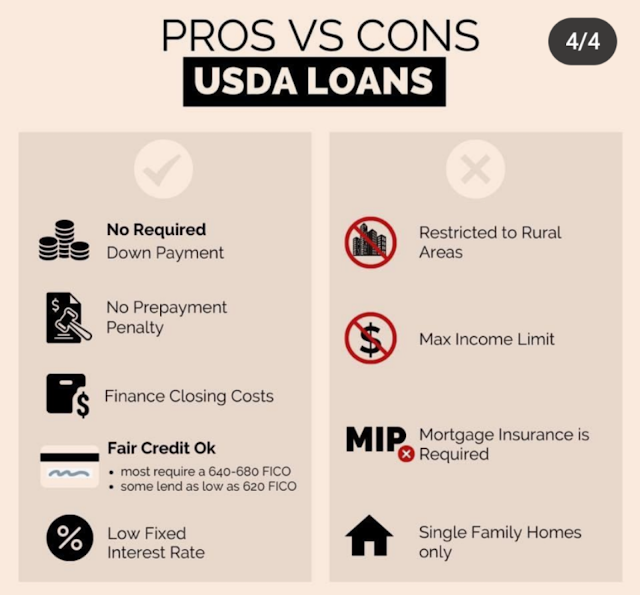
Here are the important points about Kentucky USDA Rural Housing Loans: USDA loan are only available in certain counties of Kentucky. There are two types of USDA loans available: Direct and Guaranteed.  100% financing. No down payment  USDA will go down to a no score and uses and  automated underwriting pre-approval system called GUS-Guarantee Underwriting System. The GUS findings will dictate your loan pre-approval. Kentucky USDA Rural Housing Income limits based on county and number of people in household. Must be 3 years removed from bankruptcy and foreclosure No purchase price limit Upfront funding fee of 1% of loan amount paid to RD at closing  Annual mi fee of .35% paid each month for life of loan.  Takes on average 30-45 days to close.  30 year fixed rate is the only term available and rates are usually comparable to FHA and VA government mortgage insured rates. Do not have to be a first time home buyer and can currently own another...

Manufactured Home Requirements for Kentucky FHA, VA, USDA and Conventional Mortgage Loans

Image
  KENTUCKY MORTGAGE OPTIONS FOR MANUFACTURED HOMES    Kentucky Mobile home Manufactured Homes including: Kentucky  Conventional, Kentucky FHA, Kentucky VA and Kentucky USDA home loan programs .   Kentucky Conventional Loans Up to 95 LTV on purchases 97 LTV Rate and Term REFI options for with an existing Fannie Mae loan through MH Advantage (see product snapshot for more info) Purchase and rate and term options available for  single wide , double wide and larger Cash-out options available for double-wide and larger Second home options available for double-wide and larger Down to 580 FICO Kentucky FHA Loans Up to 96.5 LTV on purchases and 97.75 LTV on Rate and Term REFIs Cash-out REFI options up to 80 LTV Purchase, cash-out and Rate and Term REFI options available for  single wide , double wide and larger Down to 550 FICO Manual underwrite options available Manufactured homes are now available on FHA 203(k) products! Kentucky VA Loans...

Kentucky FHA loans vs Kentucky USDA Loans for Kentucky Home buyers.

Criteria Loan Type FHA USDA Down Payment 3.5% 0% – None PMI .85% 0.35% Funding Fee * 1.75 1.0 Limits (loan) Per County None Limits (income) None YES -per county,etc Restricted location None YES Credit score 580 down to 3.5% 500 score with 10% down payment no minimum score There are a few other points that put the Kentucky USDA loan at an advantage over the Kentucky  FHA mortgage program  such as the appraisal value. USDA appraisal value is normally higher than the selling price. If the appraisal value is more than the purchase price, this becomes an additional advantage for borrowers as the USDA will permit you to roll in closing costs. Essentially the only issues that could be considered as drawbacks of the USDA loan are the restriction of location and the  USDA RD income limits. The location must be in a designated rural area with a total population of 20,000. This can be a setback for those who do...

Gift Funds & Gift of Equity for Kentucky FHA Mortgage Loan Approval Requirements

Image
 Kentucky FHA Gift of Equity and Gift Funds for Down Payment Requirements Gifts may be provided by: •  Borrower's family member*; •  the borrower's employer or labor union; •  a close friend with a clearly defined and documented interest in the borrower; •  a charitable organization; •  a governmental agency or public entity that has a program providing homeownership assistance to: •      low or moderate income families; or •      first-time homebuyers. *Family member defined as: •  child, foster child, parent, or grandparent; spouse or domestic partner; •  legally adopted son or daughter, including a child who is placed with the borrower by an authorized agency for legal adoption; •  brother, stepbrother, sister, stepsister; •  uncle or aunt •  son-in-law, daughter-in­ law, father-in-law, mother­ in-law, brother-in-law, or sister-in-law of the borrower. Guidelines -  Personal Gift Funds •   ...