🏠 FHA Loan
The go-to for first-time buyers and 580+ credit. Low down payment and flexible guidelines.
3.5% down · 580+ creditLearn More →🎖 VA Loan
Zero down and no monthly mortgage insurance for veterans and active-duty service members.
$0 down · VA eligibleLearn More →🌾 USDA Loan
100% financing for eligible rural and suburban Kentucky buyers within income limits.
$0 down · USDA areasLearn More →🏛 KHC Assistance
Kentucky Housing down payment assistance for first-time and repeat buyers.
Up to $12,500 assistanceLearn More →📈 Conventional
Best long-term value for stronger credit. PMI cancels at 20% equity, unlike FHA.
3% down · 620+ creditLearn More →💰 Zero Down Options
Every route to buying with nothing down in Kentucky — VA, USDA, and KHC combos.
$0 down programsLearn More →🌟 First-Time Buyers
All Kentucky first-time homebuyer programs compared in plain English.
Programs & grantsLearn More →📊 Credit Scores
What score you actually need for each loan type in 2026 — and how to raise yours.
By loan programLearn More →💬 Get Pre-Qualified
Free application review with same-day answers. We look at your credit, income, and goals — no cost, no obligation, no pressure.
📋 Compare Your Options
FHA vs. Conventional vs. USDA vs. KHC — run side by side with your actual numbers so you see the real payment before you commit.
🏠 Close & Get Your Keys
Guided from contract to closing — appraisal, title, and underwriting coordinated so you always know what happens next.

Hi, I’m Joel Lobb — a Kentucky dad who’s spent 20+ years helping families across all 120 counties buy their first home. When you call, you get me — not a phone tree. Questions on a Saturday morning? I answer.
1,300+ Kentucky families have trusted me with their mortgage — from Louisville to Lexington to the smallest towns in the state. Free application reviews, same-day pre-approvals, and honest answers about what you actually qualify for.
See What You Qualify For →Equifax, Experian and TransUnion will also no longer include medical collection debt under at least $500 on credit reports
- Get link
- X
- Other Apps
Consumer Reporting Agencies to Remove Most Medical Debt From Credit Reports
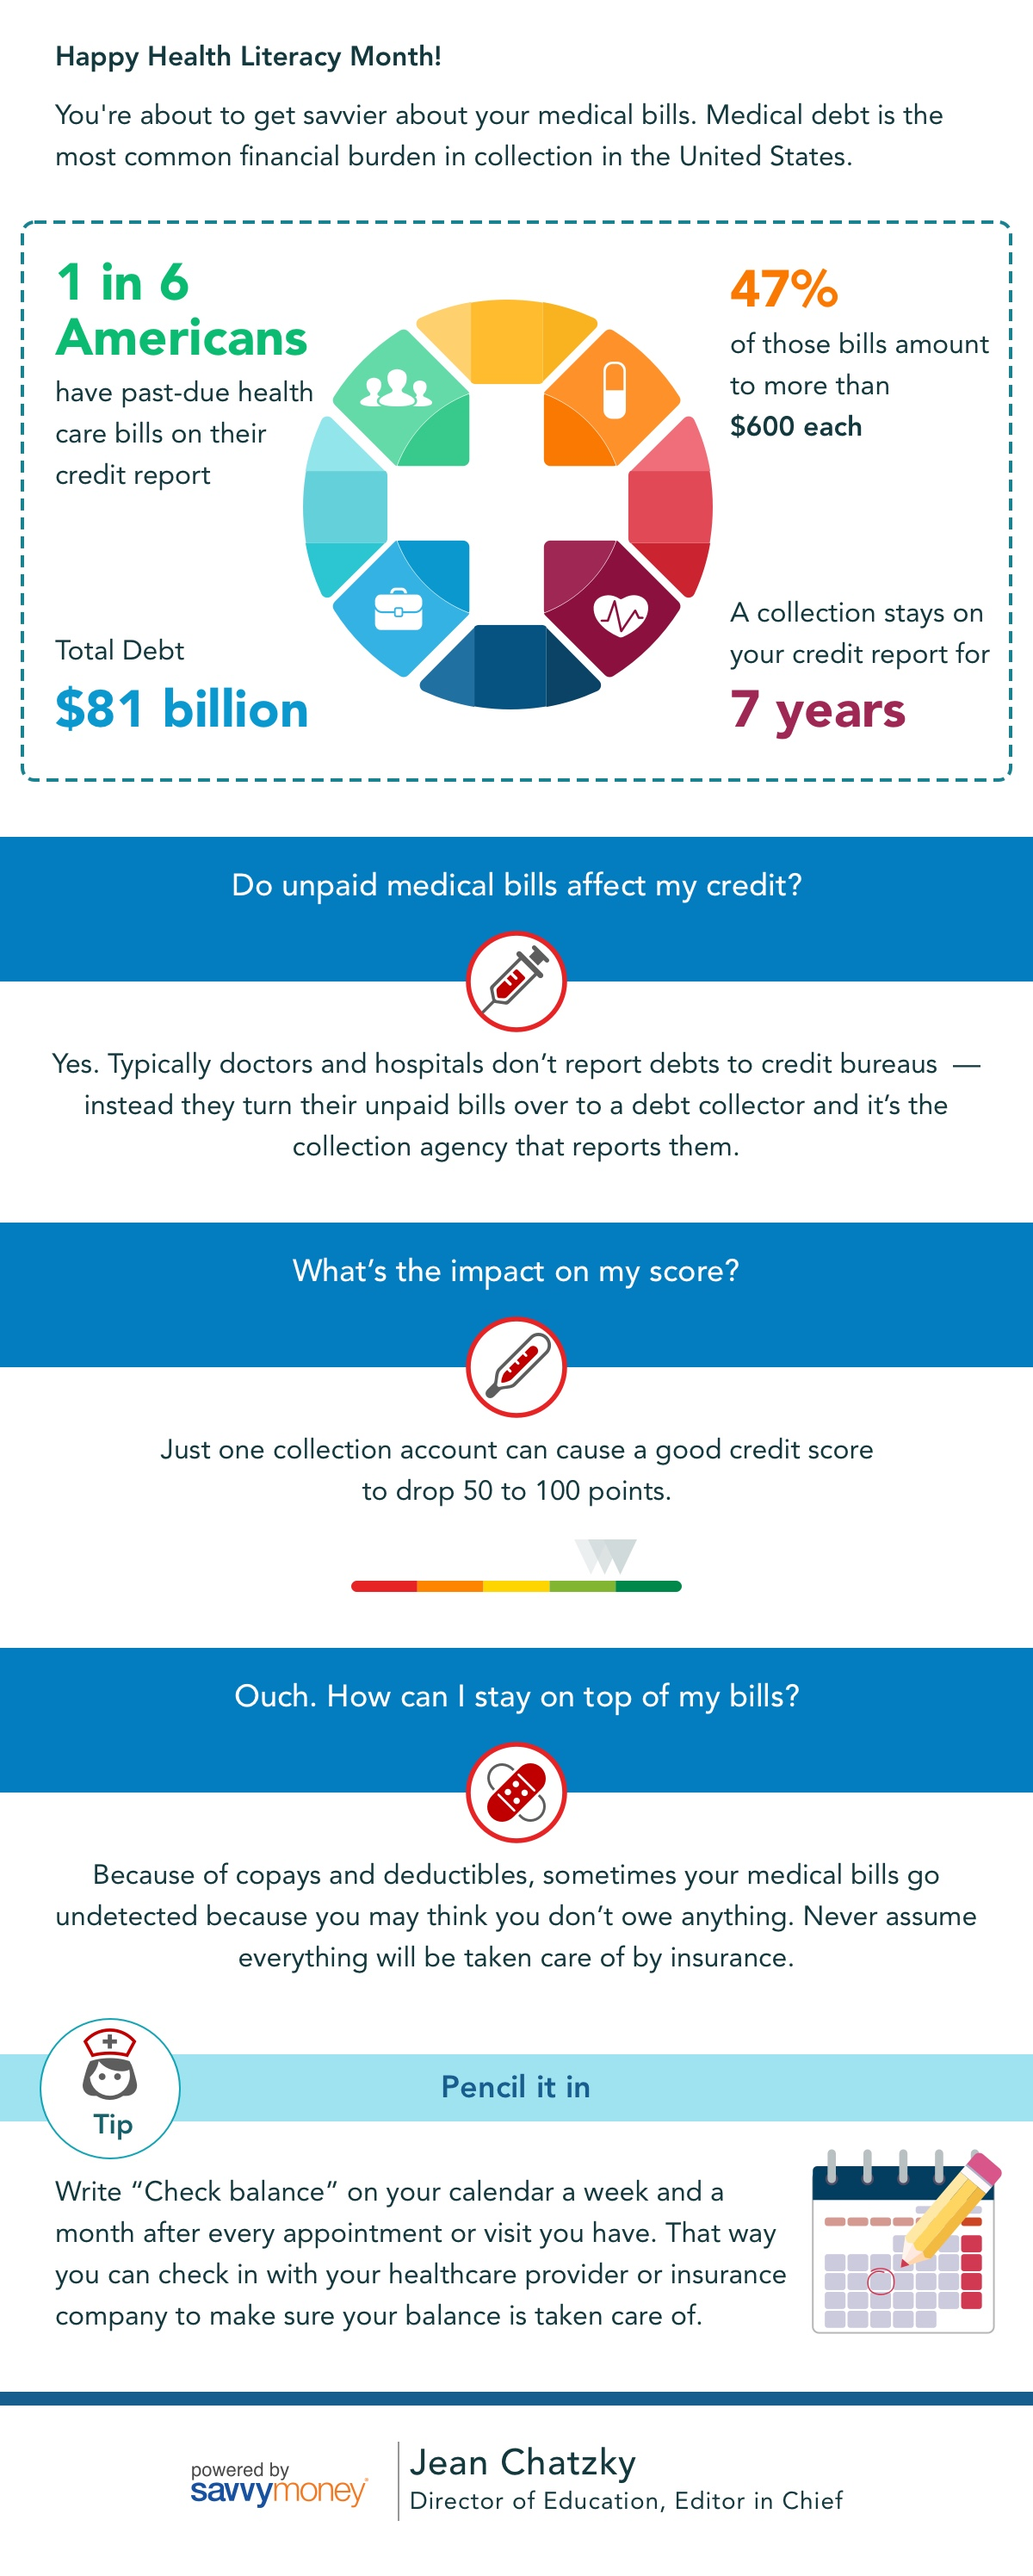
The three nationwide credit reporting agencies, Equifax, Experian and TransUnion, announced that effective July 1, 2022, they will no longer include medical debt that was paid after it was sent to collections on consumer credit reports.
The companies’ CEOs provided a joint statement on the decision to change their approach to medical collection debt reporting:
“Medical collection debt often arises from unforeseen medical circumstances. These changes are another step we’re taking together to help people across the United States focus on their financial and personal wellbeing,” said Mark W. Begor, CEO Equifax; Brian Cassin, CEO Experian; and Chris Cartwright, CEO TransUnion. “As an industry we remain committed to helping drive fair and affordable access to credit for all consumers.”
The time period before unpaid medical collection debt would appear on a consumer’s report will be increased from 6 months to one year, according to a press release, “giving consumers more time to work with insurance and/or healthcare providers to address their debt before it is reported on their credit file.”
In the first half of 2023, Equifax, Experian and TransUnion will also no longer include medical collection debt under at least $500 on credit reports.
The changes will remove nearly 70% of medical debt in collections accounts from consumer credit reports.
- Get link
- X
- Other Apps