Posts

Showing posts with the label 2nd tier entitlement VA laon
Every Kentucky Loan Type. One Local Expert.
Whether you’re buying your first home, using down payment assistance, or rebuilding credit — there’s a program that fits. Compare them side by side before you commit.

🏠 FHA Loan

The go-to for first-time buyers and 580+ credit. Low down payment and flexible guidelines.

3.5% down · 580+ creditLearn More →

🎖 VA Loan

Zero down and no monthly mortgage insurance for veterans and active-duty service members.

$0 down · VA eligibleLearn More →

🌾 USDA Loan

100% financing for eligible rural and suburban Kentucky buyers within income limits.

$0 down · USDA areasLearn More →

🏛 KHC Assistance

Kentucky Housing down payment assistance for first-time and repeat buyers.

Up to $12,500 assistanceLearn More →

📈 Conventional

Best long-term value for stronger credit. PMI cancels at 20% equity, unlike FHA.

3% down · 620+ creditLearn More →

💰 Zero Down Options

Every route to buying with nothing down in Kentucky — VA, USDA, and KHC combos.

$0 down programsLearn More →

🌟 First-Time Buyers

All Kentucky first-time homebuyer programs compared in plain English.

Programs & grantsLearn More →

📊 Credit Scores

What score you actually need for each loan type in 2026 — and how to raise yours.

By loan programLearn More →

How Much House Can I Afford in Kentucky? 2026 DTI Limits by Loan Program

Image
By Joel Lobb, Kentucky Mortgage Loan Officer · NMLS #57916 · Updated September 24, 2026 Short answer: Kentucky lenders decide how much you qualify for using your debt-to-income ratio (DTI) . Your new house payment usually needs to stay near 29–31% of your gross monthly income , and your house payment plus all other debts can reach 41–50% depending on the loan program. A household earning $75,000 with $450 a month in debts typically qualifies for about $219,000 (USDA) to $303,000 (conventional) at today's rates. Your loan program sets the DTI limit, and the DTI limit sets your price range. "How much house can I afford?" is the first question almost every Kentucky homebuyer asks me, and online calculators rarely agree. That is because each loan program (FHA, VA, USDA, KHC, and conventional) uses different debt ratio limits, mortgage insurance, and down payments. This guide shows you exactly how lenders run the numbers, gives you a calculator built on Kentucky a...
Getting a Kentucky Mortgage in 3 Simple Steps
No confusing paperwork trails. No surprise fees. A clear path from first call to keys in hand.
01

💬 Get Pre-Qualified

Free application review with same-day answers. We look at your credit, income, and goals — no cost, no obligation, no pressure.

02

📋 Compare Your Options

FHA vs. Conventional vs. USDA vs. KHC — run side by side with your actual numbers so you see the real payment before you commit.

03

🏠 Close & Get Your Keys

Guided from contract to closing — appraisal, title, and underwriting coordinated so you always know what happens next.

Watch: Kentucky Mortgage Guides
Straight answers from my YouTube channel — no jargon, no sales pitch.
▶ More videos on my YouTube channel →
Joel Lobb and family - Kentucky mortgage loan officer
Kentucky Local. Not a Call Center.

Hi, I’m Joel Lobb — a Kentucky dad who’s spent 20+ years helping families across all 120 counties buy their first home. When you call, you get me — not a phone tree. Questions on a Saturday morning? I answer.

1,300+ Kentucky families have trusted me with their mortgage — from Louisville to Lexington to the smallest towns in the state. Free application reviews, same-day pre-approvals, and honest answers about what you actually qualify for.

See What You Qualify For →

Can you have 2 Kentucky VA Loans?

Image
A Kentucky Veteran Can Have Multiple VA Loans: In the most basic of terms, VA Second-Tier Entitlement gives a qualified military person the ability to have two KY VA mortgages out simultaneously. VA will allow a Kentucky Veteran to have multiple Kentucky  VA loans provided they meet the required GNMA 25 percent guaranty. Are you unsure of how to calculate the maximum loan amount for a Veteran based on their used entitlement? I am Kentucky Veteran myself and have done over 50 VA loans for past customers in Kentucky. I am here to help with your Kentucky VA mortgage questions! Click here and download an interactive, Kentucky Mortgage VA Entitlement and Loan Amount worksheet  to help you determine their Kentucky VA Home loan maximum loan amount. This worksheet also works great to determine the maximum loan amount for a Veteran when they are buying a home over their county loan limit. First let’s explain the difference between entitlement and maximum loan amount. E...

Kentucky VA Home Loan Mortgage Lender: Understanding Your Kentucky VA Home Loan Benefits

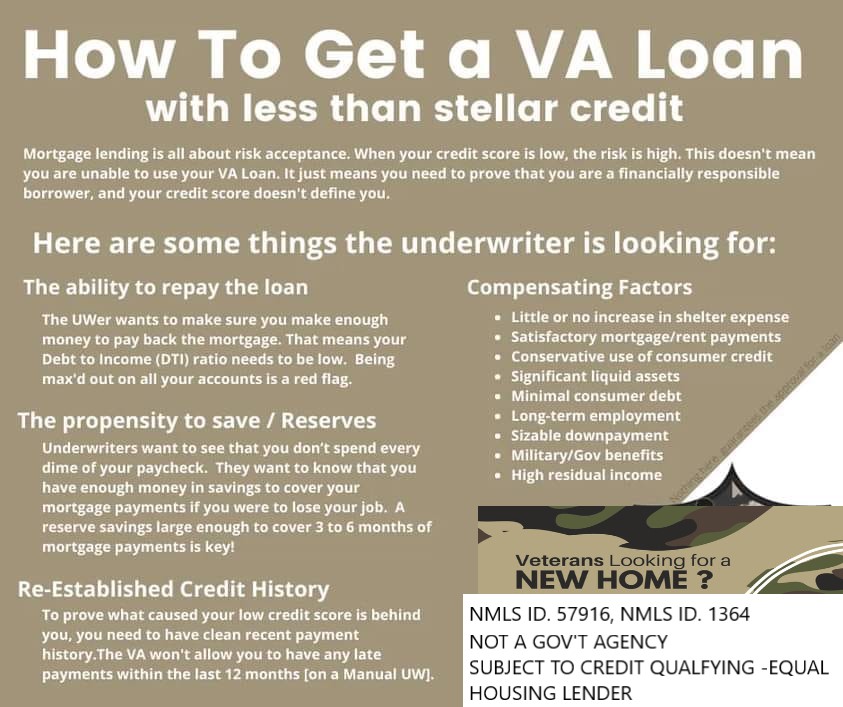
Louisville Kentucky VA Home Loan Mortgage Lender: Understanding Your Kentucky VA Home Loan Benefits Kentucky VA Home Loan Mortgage Lender: 👇👇👇👇👇👇👇 Is your credit score high enough for a  Kentucky VA Home Loan Approval? Usually, 620 or Higher is better for 2 reasons lower rate and less stipulations from the underwriter Do you have sufficient credit depth for a Kentucky VA Home Loan Approval? Generally, all on-time payments in the last 12 months. They like to see two-three paid on time  for the last 12 months Do you make enough money to cover all your debts, including the new Kentucky VA mortgage? Debts divided by your gross monthly income is lower than 50%. I have seen many exceptions to this with compensating factors. I have seen as high as 78% debt ratio get approved through the AUS if you have high credit scores (720 or higher, good residual income, a lot of assets, ie money in the bank, retirement, etc. -Do you have a high probability o...

Louisville Kentucky VA Home Loan Mortgage Lender: How to Get Approved for a Kentucky VA Home Mortgag...

Image
Louisville Kentucky VA Home Loan Mortgage Lender: How to Get Approved for a Kentucky VA Home Mortgag... : Basic Understanding of a Kentucky VA Mortgage Loan Approval Process. The VA makes a guarantee to the lending institution (the insurance)-for... Basic Understanding of a Kentucky VA Mortgage Loan Approval Process. The VA makes a guarantee to the lending institution (the insurance)-for 25% of the loan amount (from a lenders perspective the effective LTV is 75%). Because the risk to the bank is reduced, the bank can provide more affordable loans to the Veteran: • Eliminating the need for a down payment (100% Mortgage) • Provides the Veterans favorable interest rates • Eliminating Mortgage Insurance (NO PMI) Crushing the Myths of the VA Loan • VA Mortgage Benefits do not expire. • You can use your VA benefits as many times as you wish. • You can have more than 1 at a time. (See occupancy rules) • There is no limit to the size of a VA loan. (There is a county loan limit, but veterans ca...

Louisville Kentucky VA Home Loan Mortgage Lender: Tips on getting a Kentucky VA Mortgage Guidelines ...

Image
Louisville Kentucky VA Home Loan Mortgage Lender: Tips on getting a Kentucky VA Mortgage Guidelines ... : Getting  your Louisville  Kentucky VA  Loan  Approval Run a 25-year loan if you are not getting an approval with a 30-year. Even with higher... Run a 25-year loan if you are not getting an approval with a 30-year. Even with higher ratios, 25-year loans are considered lower risk and can be key to getting an Approve Eligible • You can do a VA IRRRL on a property that the veteran no longer lives in • Payoff debts at closing with seller concessions. When writing the offer, this information goes in the “under additional provisions or other terms” section • No seasoning requirement for being added to the title (No flip rule) • Only type of loan where an SAR Underwriter can adjust the value after a secondary review in Tidewater with a request from the borrower. That gives us two chances to increase the value if it comes in under. • You can have more than one at the same...