Posts

Showing posts with the label Rural Housing Guidelines
Every Kentucky Loan Type. One Local Expert.
Whether you’re buying your first home, using down payment assistance, or rebuilding credit — there’s a program that fits. Compare them side by side before you commit.

🏠 FHA Loan

The go-to for first-time buyers and 580+ credit. Low down payment and flexible guidelines.

3.5% down · 580+ creditLearn More →

🎖 VA Loan

Zero down and no monthly mortgage insurance for veterans and active-duty service members.

$0 down · VA eligibleLearn More →

🌾 USDA Loan

100% financing for eligible rural and suburban Kentucky buyers within income limits.

$0 down · USDA areasLearn More →

🏛 KHC Assistance

Kentucky Housing down payment assistance for first-time and repeat buyers.

Up to $12,500 assistanceLearn More →

📈 Conventional

Best long-term value for stronger credit. PMI cancels at 20% equity, unlike FHA.

3% down · 620+ creditLearn More →

💰 Zero Down Options

Every route to buying with nothing down in Kentucky — VA, USDA, and KHC combos.

$0 down programsLearn More →

🌟 First-Time Buyers

All Kentucky first-time homebuyer programs compared in plain English.

Programs & grantsLearn More →

📊 Credit Scores

What score you actually need for each loan type in 2026 — and how to raise yours.

By loan programLearn More →

Kentucky Home Inspection vs. Appraisal: Key Differences

Image
By Joel Lobb, Mortgage Loan Officer · NMLS #57916 · Updated September 12, 2026 The difference between a Kentucky home inspection and a Kentucky appraisal is their purpose: an inspection evaluates the home's condition, while an appraisal estimates its market value for the mortgage process. One does not replace the other. A homebuyer's two questions: What needs attention, and what is the property worth? Buying in Louisville, Lexington, Bowling Green, or elsewhere in Kentucky? Before paying for inspections and appraisal services, understand who orders each report, what it covers, and how the results may affect your purchase. In this guide Comparison Inspection checklist Appraisal process Costs and timing Video FAQs Kentucky home inspection vs. appraisal: the difference HOME INSPECTION Condition What needs attention? Roof · Foundation · Plumbing Electrical · Heating and cooling Usually arranged by: the buyer Result: an inspection report Next step: review repairs and f...
Getting a Kentucky Mortgage in 3 Simple Steps
No confusing paperwork trails. No surprise fees. A clear path from first call to keys in hand.
01

💬 Get Pre-Qualified

Free application review with same-day answers. We look at your credit, income, and goals — no cost, no obligation, no pressure.

02

📋 Compare Your Options

FHA vs. Conventional vs. USDA vs. KHC — run side by side with your actual numbers so you see the real payment before you commit.

03

🏠 Close & Get Your Keys

Guided from contract to closing — appraisal, title, and underwriting coordinated so you always know what happens next.

Watch: Kentucky Mortgage Guides
Straight answers from my YouTube channel — no jargon, no sales pitch.
▶ More videos on my YouTube channel →
Joel Lobb and family - Kentucky mortgage loan officer
Kentucky Local. Not a Call Center.

Hi, I’m Joel Lobb — a Kentucky dad who’s spent 20+ years helping families across all 120 counties buy their first home. When you call, you get me — not a phone tree. Questions on a Saturday morning? I answer.

1,300+ Kentucky families have trusted me with their mortgage — from Louisville to Lexington to the smallest towns in the state. Free application reviews, same-day pre-approvals, and honest answers about what you actually qualify for.

See What You Qualify For →

New USDA Loan Guidelines for Kentucky Home Buyers

Image
I wanted to share an important update regarding the  USDA Single Family Housing Guaranteed Loan Program (SFHGLP)  for Kentucky home buyers.  The USDA has recently proposed revisions to several chapters of their t echnical Handbook 1-3555, which may impact various aspects of the loan process. These proposed changes are currently open for comment until December 8, 2024, with final publication expected soon. Here’s an overview of the proposed revisions: Key Proposed Updates to Kentucky Rural Housing USDA Guidelines: Seller Concessions : Clarifies that funds provided by the seller to pay the buyer’s real estate commission fees are excluded from the 6% seller concession cap. Refinancing Eligibility : The seasoning period for an existing loan to be eligible for refinancing has been updated to  180 days . Payment History Requirement : To qualify for a refinance, the existing loan must not have any delinquencies greater than 30 days within the previous 180-day period. Manuf...

Kentucky FHA Mortgage Loans vs Kentucky USDA Rural Housing Loans Compared

Image
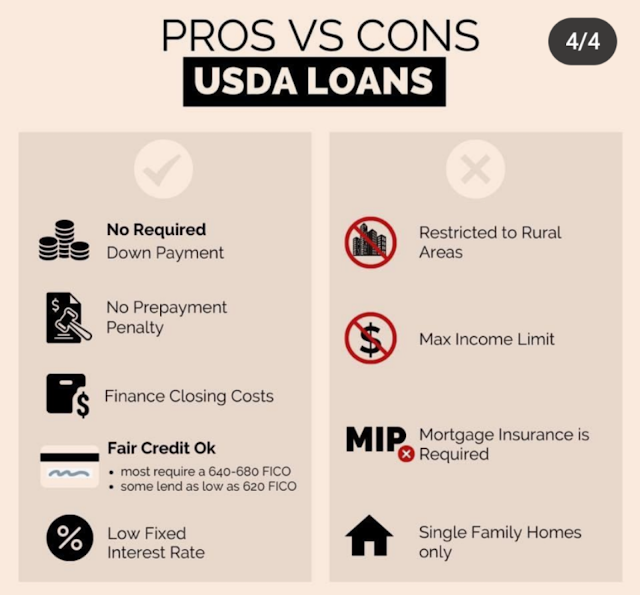
Here are the important points about Kentucky USDA Rural Housing Loans: USDA loan are only available in certain counties of Kentucky. There are two types of USDA loans available: Direct and Guaranteed.  100% financing. No down payment  USDA will go down to a no score and uses and  automated underwriting pre-approval system called GUS-Guarantee Underwriting System. The GUS findings will dictate your loan pre-approval. Kentucky USDA Rural Housing Income limits based on county and number of people in household. Must be 3 years removed from bankruptcy and foreclosure No purchase price limit Upfront funding fee of 1% of loan amount paid to RD at closing  Annual mi fee of .35% paid each month for life of loan.  Takes on average 30-45 days to close.  30 year fixed rate is the only term available and rates are usually comparable to FHA and VA government mortgage insured rates. Do not have to be a first time home buyer and can currently own another...

Kentucky USDA Rural Development Loans for 2023 Upfront Mortgage Insurance and Annual Fee Changes for Conditional Commitments

KENTUCKY USDA RURAL HOUSING CONDITIONAL COMMITMENT FOR 2023  With the start of Fiscal Year 2023 (FY) soon approaching, please take a few minutes to review the Single-Family Housing Guaranteed Loan Program (SFHGLP) Conditional Commitment process. We hope you find this information helpful. FY 2023 will begin October 1, 2022 and ends at the close of business September 30, 2023. Fee Structures: An upfront guarantee fee of 1.00 percent and an annual fee of .35 percent will apply to both purchase and refinance transactions for Kentucky USDA Rural Development Loans for 2023 Issuance of : At the beginning of each fiscal year, funding for the guaranteed loan program is not available for a short period of time – approximately two weeks. USDA anticipates this brief lapse in funding to continue for FY 2023. During the temporary lapse in funding, Rural Development - Rural Housing Service (RHS) will issue Conditional Commitments (Form RD 3555-18/18E) “subject to the availability of commitment au...

What are the Kentucky USDA Mortgage Loan Requirements?

Image
Kentucky Mortgage USDA Loan Requirements What are the Kentucky USDA Mortgage Loan Requirements? To decide if you qualify for an USDA Mortgage Loan, we will look at: •Your income and your monthly expenses. Standard debt-to-income ratios are 29/41 for USDA Loans. These ratios may be exceeded with compensation factors. •Your credit history (this is important, but USDA’s credit standards are flexible). A FICO score of 620 or above is required for all loans •Your overall pattern rather than to individual problems you may have had. To be eligible for an USDA mortgage, your monthly housing costs (mortgage principal and interest, property taxes and insurance) must meet a specified percentage of your gross monthly income (29% ratio). Your credit background will be fairly considered. At least a 620 FICO credit score is required to obtain an USDA approval through Lending. You must also have enough income to pay your housing costs plus all additional monthly debt (41% ratio...

2014 Income Limits for the Kentucky USDA Rural Housing Single Family Guaranteed Loan Program

Image
The 2014 Income Limits for the Kentucky USDA Rural Housing  Single Family Guaranteed Loan Program were published on February 12, 2014.  The Ky USDA Rural Housing Guaranteed Underwriting System and the Income Eligibility calculator for Kentucky USDA Home Buyers have been updated with the new income limits.  The new income limit changes will apply to all loans submitted through GUS on and after February 12, 2014. Kentucky USDA Rural Housing 2014 Income limits can be found online at:   http://www.rurdev.usda.gov/SupportDocuments/KY%20GRH.pdf Fill out my form!

Kentucky Mortgage Loan Approval for USDA, FHA, VA, and Fannie Mae with a previous short sale or foreclosure. How long do you have to wait?

Image
 Obtaining new financing after a Short Sale or Foreclosure for a Kentucky USDA, FHA, VA, and Fannie Mae Loan?   Kentucky Mortgage Short Sale: Conventional Loans Require: Minimum 2 years with restrictions up to 7 years 2 to 4 years - 80% maximum LTV 4 to 7 years - 90% maximum LTV 7 years and after allow for maximum standard financing Kentucky FHA and Kentucky VA Loans Require: 3 years, with exceptions possible for less time if borrower's credit and mortgage payments were in good standing prior and up to date of Short Sale   Kentucky Mortgage Foreclosure: Conventional Loans Require: 7 years, with exceptions considered between 3 to 7 years if significant extenuating circumstances exist Kentucky FHA and Kentucky VA Loans Require: FHA: 3 years, with exceptions possible for less time if significant extenuating circumstances exist VA: 3 years, with exceptions possible for less time if significant extenuating circumstances ex...

What are the requirements for Financing on a Guaranteed Rural Housing Loan in Kentucky?

Image
Kentucky Guaranteed Rural Housing (102% Financing on appraised value)     see the full video below on qualifying for a Kentucky USDA Mortgage loan below: 👇👇👇👇 If you want a personalized answer for your unique situation call, text, or email me or visit my website below: Joel Lobb Mortgage Loan Officer Individual NMLS ID #57916 American Mortgage Solutions, Inc. 10602 Timberwood Circle Louisville, KY 40223 Company NMLS ID #1364 click here for directions to our office Text/call:      502-905-3708 fax:            502-327-9119 email:          kentuckyloan@gmail.com https://www.mylouisvillekentuckymortgage.com/ Disclaimer: No statement on this site is a commitment to make a loan. Loans are subject to borrower qualifications, including income, property evaluation, sufficient equity in the home to meet Loan-to-Value requirements, and final credit ap...