Posts

Showing posts with the label Kentucky VA Home Loans
Every Kentucky Loan Type. One Local Expert.
Whether you’re buying your first home, using down payment assistance, or rebuilding credit — there’s a program that fits. Compare them side by side before you commit.

🏠 FHA Loan

The go-to for first-time buyers and 580+ credit. Low down payment and flexible guidelines.

3.5% down · 580+ creditLearn More →

🎖 VA Loan

Zero down and no monthly mortgage insurance for veterans and active-duty service members.

$0 down · VA eligibleLearn More →

🌾 USDA Loan

100% financing for eligible rural and suburban Kentucky buyers within income limits.

$0 down · USDA areasLearn More →

🏛 KHC Assistance

Kentucky Housing down payment assistance for first-time and repeat buyers.

Up to $12,500 assistanceLearn More →

📈 Conventional

Best long-term value for stronger credit. PMI cancels at 20% equity, unlike FHA.

3% down · 620+ creditLearn More →

💰 Zero Down Options

Every route to buying with nothing down in Kentucky — VA, USDA, and KHC combos.

$0 down programsLearn More →

🌟 First-Time Buyers

All Kentucky first-time homebuyer programs compared in plain English.

Programs & grantsLearn More →

📊 Credit Scores

What score you actually need for each loan type in 2026 — and how to raise yours.

By loan programLearn More →

Kentucky Home Inspection vs. Appraisal: Key Differences

Image
By Joel Lobb, Mortgage Loan Officer · NMLS #57916 · Updated September 12, 2026 The difference between a Kentucky home inspection and a Kentucky appraisal is their purpose: an inspection evaluates the home's condition, while an appraisal estimates its market value for the mortgage process. One does not replace the other. A homebuyer's two questions: What needs attention, and what is the property worth? Buying in Louisville, Lexington, Bowling Green, or elsewhere in Kentucky? Before paying for inspections and appraisal services, understand who orders each report, what it covers, and how the results may affect your purchase. In this guide Comparison Inspection checklist Appraisal process Costs and timing Video FAQs Kentucky home inspection vs. appraisal: the difference HOME INSPECTION Condition What needs attention? Roof · Foundation · Plumbing Electrical · Heating and cooling Usually arranged by: the buyer Result: an inspection report Next step: review repairs and f...
Getting a Kentucky Mortgage in 3 Simple Steps
No confusing paperwork trails. No surprise fees. A clear path from first call to keys in hand.
01

💬 Get Pre-Qualified

Free application review with same-day answers. We look at your credit, income, and goals — no cost, no obligation, no pressure.

02

📋 Compare Your Options

FHA vs. Conventional vs. USDA vs. KHC — run side by side with your actual numbers so you see the real payment before you commit.

03

🏠 Close & Get Your Keys

Guided from contract to closing — appraisal, title, and underwriting coordinated so you always know what happens next.

Watch: Kentucky Mortgage Guides
Straight answers from my YouTube channel — no jargon, no sales pitch.
▶ More videos on my YouTube channel →
Joel Lobb and family - Kentucky mortgage loan officer
Kentucky Local. Not a Call Center.

Hi, I’m Joel Lobb — a Kentucky dad who’s spent 20+ years helping families across all 120 counties buy their first home. When you call, you get me — not a phone tree. Questions on a Saturday morning? I answer.

1,300+ Kentucky families have trusted me with their mortgage — from Louisville to Lexington to the smallest towns in the state. Free application reviews, same-day pre-approvals, and honest answers about what you actually qualify for.

See What You Qualify For →

What is the minimum Credit Score Needed to Buy a House and get a Kentucky Mortgage Loan?

Image
Kentucky Home Buyers: What Credit Score Do You Need? Buying a home in Kentucky? Your credit score plays a crucial role in determining which mortgage loans you qualify for and how much you’ll pay in interest rates . Understanding the minimum credit score requirements for FHA, VA, USDA, and Conventional loans can help you prepare for homeownership and secure the best loan options. While there's no single, simple answer, this guide will break down the minimum credit score requirements for various Kentucky mortgage options, empowering you to understand where you stand and how to achieve your homeownership goals. We'll cut through the confusion and give you the straight facts! Why Your Credit Score Matters: More Than Just a Number Think of your credit score as your financial reputation. Lenders use it to assess the risk of lending you money. A higher score signals lower risk, translating to better interest rates, more favorable loan terms, and potentially lower down payment re...

How do collections and charge offs on the credit report affect a Kentucky VA Mortgage Loan Approval?

Image
Kentucky VA Loan Guidelines: Collections, Charge-Offs, Judgments and Liens Many Kentucky veterans are worried that old collections or charge-offs will automatically stop a VA home loan approval. In most cases, that is not true. The VA underwriter looks at the whole credit picture, not just one negative item, and wants to know whether you are a satisfactory long-term credit risk. This guide explains how Kentucky VA lenders typically treat collection accounts, charge-offs, judgments and liens when you apply for a VA mortgage. VA credit guidelines can be flexible, but every file is different. The best way to know where you stand is to have your full credit report reviewed by a VA-approved lender who understands Kentucky guidelines. How VA Views Collection Accounts VA does not automatically require every collection to be paid before you can close on a home. Instead, the underwriter reviews the type, age, size and pattern of the collection accounts and whethe...

Job Requirements and Employment History for a Kentucky VA loan Approval.

Image
Mortgage Employment or Job History Requirements for a VA Loan Approval in Kentucky  Gaps in Employment A borrower who has no verifiable employment for 6 months or longer is deemed to have a gap in employment.   VA :  VA does not address gaps in employment and generally does not consider non military employment less than 12 months as stable and reliable. Any exceptions based on the loan as a whole is underwriter discretion. Medical or Temporary Leave Income The borrower has taken a temporary leave of absence from work typically for medical leave such as maternity, illness, surgery, or on the job injury.  This leave is short term in nature and the borrower is still employed with their same employer prior to the leave of absence.    VA : Borrower’s on temporary leave are not eligible for a loan transaction.    Frequent Job Changes Frequent job changes may i...

Can you have 2 Kentucky VA Loans?

Image
A Kentucky Veteran Can Have Multiple VA Loans: In the most basic of terms, VA Second-Tier Entitlement gives a qualified military person the ability to have two KY VA mortgages out simultaneously. VA will allow a Kentucky Veteran to have multiple Kentucky  VA loans provided they meet the required GNMA 25 percent guaranty. Are you unsure of how to calculate the maximum loan amount for a Veteran based on their used entitlement? I am Kentucky Veteran myself and have done over 50 VA loans for past customers in Kentucky. I am here to help with your Kentucky VA mortgage questions! Click here and download an interactive, Kentucky Mortgage VA Entitlement and Loan Amount worksheet  to help you determine their Kentucky VA Home loan maximum loan amount. This worksheet also works great to determine the maximum loan amount for a Veteran when they are buying a home over their county loan limit. First let’s explain the difference between entitlement and maximum loan amount. E...

What are the requirements to buy a house in Kentucky in 2023?

Image
Credit Score and Income Requirements to Buy a Home in Kentucky in 2023 KENTUCKY CONVENTIONAL Get your fixed interest rates for eligible buyers.620 minimum credit score 3% down payment  4-7 years removed from Bankruptcy Depending of if Chapter 7 or 13  Max Loan is $647,200  in Kentucky 2 Year work history but does not have to be same job KENTUCKY FHA   MORTGAGES Government-backed loans with flexible guidelines. 500 minimum credit score with 10% down payment 3.5% down payment with 580 credit score 2 years removed from bankruptcy Can be combined with down payment grants for $0 down payment Max loan for FHA in Kentucky is $420,680 2 year work history with no gaps over 6 months KENTUCKY USDA   MORTGAGES Government-backed loans with flexible guidelines. Zero Down Payment No Minimum Credit Score, 640 is preferred with most USDA Kentucky Lenders 3 years removed from Bankruptcy Max Income and Property Map Eligibility Re...

Kentucky VA Home Loan Mortgage Lender: Understanding Your Kentucky VA Home Loan Benefits

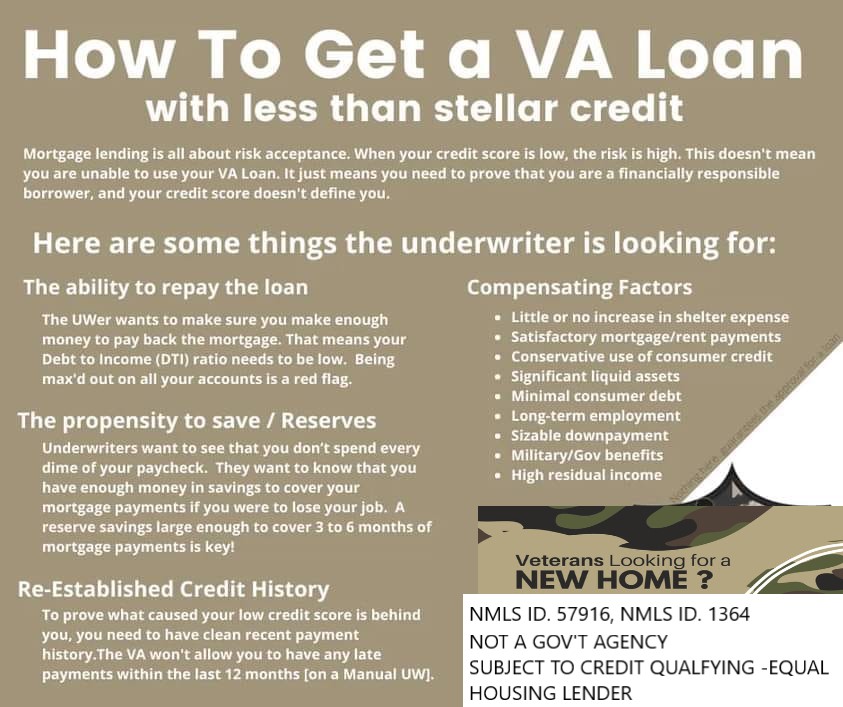
Louisville Kentucky VA Home Loan Mortgage Lender: Understanding Your Kentucky VA Home Loan Benefits Kentucky VA Home Loan Mortgage Lender: 👇👇👇👇👇👇👇 Is your credit score high enough for a  Kentucky VA Home Loan Approval? Usually, 620 or Higher is better for 2 reasons lower rate and less stipulations from the underwriter Do you have sufficient credit depth for a Kentucky VA Home Loan Approval? Generally, all on-time payments in the last 12 months. They like to see two-three paid on time  for the last 12 months Do you make enough money to cover all your debts, including the new Kentucky VA mortgage? Debts divided by your gross monthly income is lower than 50%. I have seen many exceptions to this with compensating factors. I have seen as high as 78% debt ratio get approved through the AUS if you have high credit scores (720 or higher, good residual income, a lot of assets, ie money in the bank, retirement, etc. -Do you have a high probability o...

Louisville Kentucky VA Home Loan Mortgage Lender: How to Get Approved for a Kentucky VA Home Mortgag...

Image
Louisville Kentucky VA Home Loan Mortgage Lender: How to Get Approved for a Kentucky VA Home Mortgag... : Basic Understanding of a Kentucky VA Mortgage Loan Approval Process. The VA makes a guarantee to the lending institution (the insurance)-for... Basic Understanding of a Kentucky VA Mortgage Loan Approval Process. The VA makes a guarantee to the lending institution (the insurance)-for 25% of the loan amount (from a lenders perspective the effective LTV is 75%). Because the risk to the bank is reduced, the bank can provide more affordable loans to the Veteran: • Eliminating the need for a down payment (100% Mortgage) • Provides the Veterans favorable interest rates • Eliminating Mortgage Insurance (NO PMI) Crushing the Myths of the VA Loan • VA Mortgage Benefits do not expire. • You can use your VA benefits as many times as you wish. • You can have more than 1 at a time. (See occupancy rules) • There is no limit to the size of a VA loan. (There is a county loan limit, but veterans ca...

Kentucky First Time Home Buyer Programs to Consider for 2022 Kentucky Homebuyers.

Image
First Time Home Buyer Programs to Consider for 2022 Kentucky Homebuyers. Zero Down Mortgage Loans in Kentucky The Kentucky VA and the Kentucky USDA Home Loan Program both offer a zero down loan program for individuals and/or properties that meet their criteria. If you need down payment assistance, KHC offers up to $7,500 for assistance to buy your Kentucky home if you are lacking the down payment requirements for FHA or Fannie Mae below. Some Kentucky FHA owned HUD properties are available with as little as $100 down. Three Percent Down Mortgage Loans in Kentucky Fannie Mae/Freddie Mac conventional loans are available with down payments as low as 3% on single-family homes, including eligible condos, co-ops, and some manufactured homes. Fixed-rate mortgages with up to 30-year terms and ARMs are available. Three and 1/2 Percent Down Mortgage Loans in Kentucky The Federal Housing Administration (or FHA) loan program can allow as little as 3.5% down, and it is more lenient than most o...